StrategiesVWAP Reversion Intraday
🔄 Mean ReversionIntermediate
VWAP Reversion Intraday
Intraday strategy that exploits extreme deviations of price from the daily VWAP, a key reference point for institutional operators.
StocksIndicesCrypto
Typical R/R
1:1.5 — 1:2.5
Win Rate
55–60%
Timeframe
5M, 15M, 1H
Category
Mean Reversion
[ STRATEGY SCHEMA ]
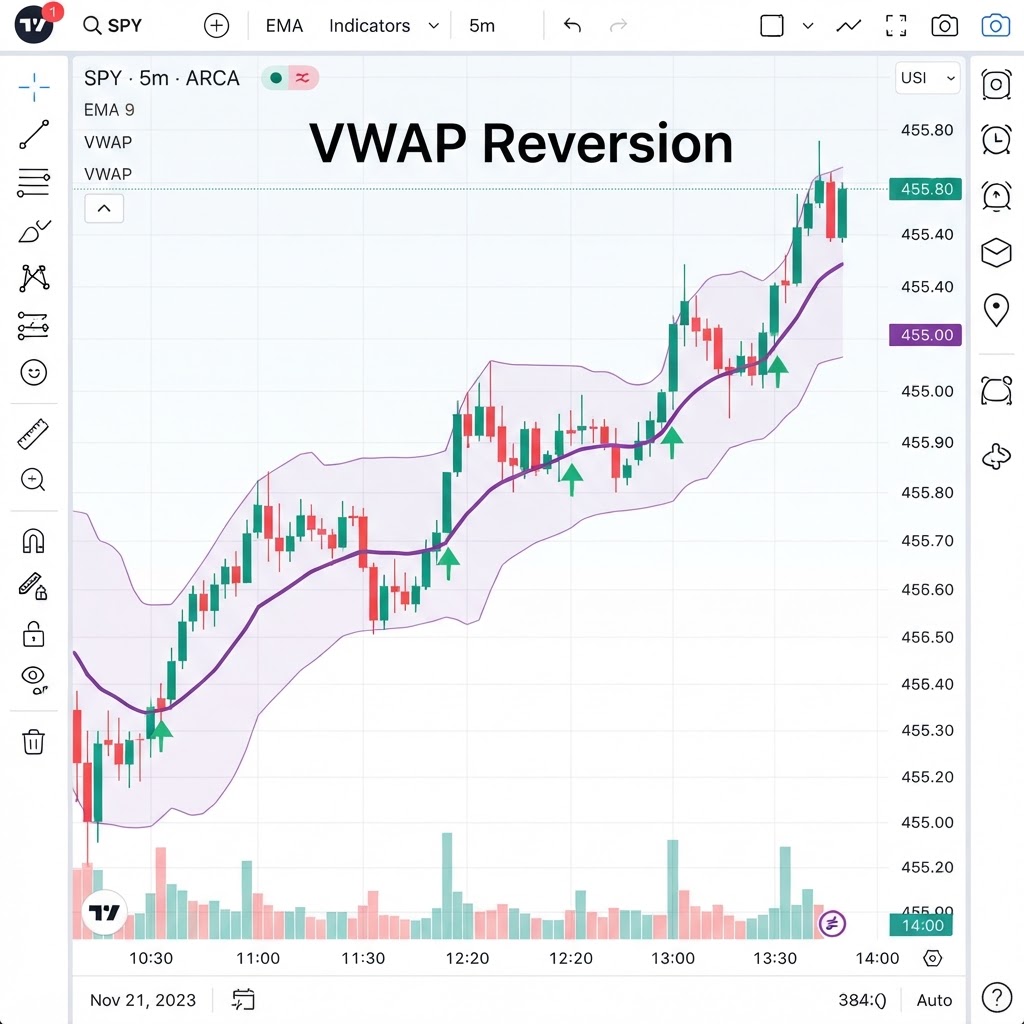
[ MARKET LOGIC ]
VWAP represents the volume-weighted average price of the day. When price moves excessively away (beyond standard deviation bands) without a news catalyst, it tends to return toward VWAP during the session.
PROS
Reference used by institutions
Great for day trading
CONS
Requires constant intraday monitoring
Less effective on illiquid assets
What are the setup conditions for VWAP Reversion Intraday?
1
Draw the daily VWAP with standard deviation bands (±1, ±2)2
Price reaches the ±2 band without relevant news in progress3
Rejection candle on the extreme band4
Volume declining compared to the move that brought price thereWhich filters improve the quality of the signal?
Avoid during earnings or scheduled macro news
Works best on highly liquid stocks/assets
[ RELATED STRATEGIES ]